What is Backtesting in Trading
Backtesting fundamentals: historical data analysis, performance metrics, and validation techniques for trading strategies.

Marketing

-
Readers ask whether they can backtest for free, so the guidance now covers TradingView’s Strategy Tester and free-account Bar Replay timeframe limits, and says TradersPost does not run backtests.
Backtesting is an essential technique used by traders to evaluate the performance of a trading strategy using historical market data. By simulating trades based on past price movements, traders can assess the potential profitability and risk characteristics of their strategies before risking real capital. This article will guide you through the intricacies of backtesting, including its key components, common pitfalls, and how TradersPost can streamline your transition from backtesting to live trading execution.

Understanding Backtesting
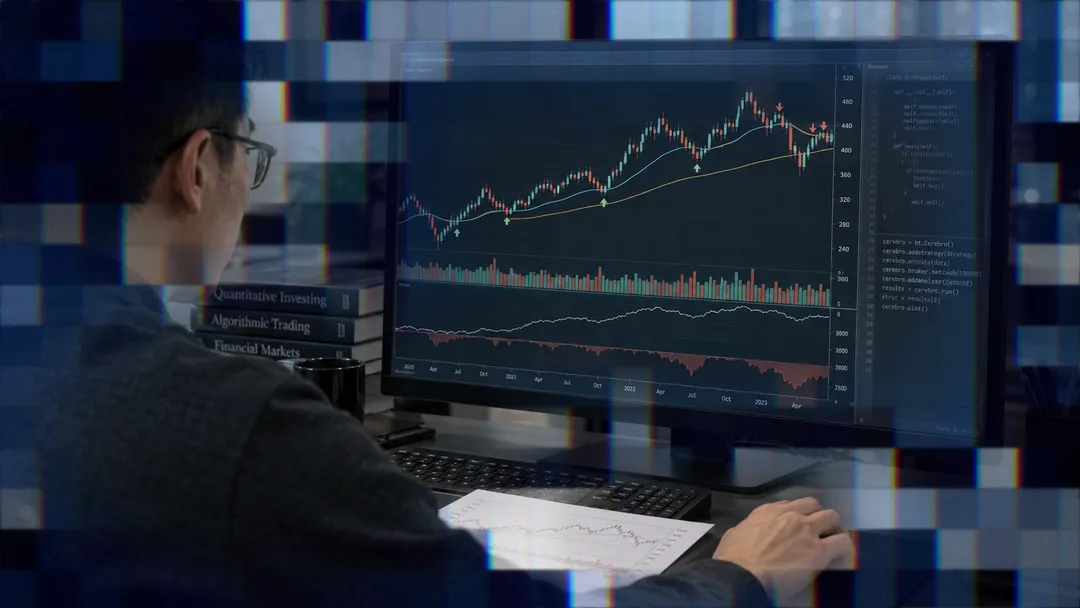
Backtesting simulates how your trading strategy would have performed during specific historical periods. It's a crucial process that helps identify whether your strategy has the potential for profitability and provides insights into performance metrics such as win rate, maximum drawdown, and risk-adjusted returns. TradersPost enhances this process by providing seamless integration for automated execution once your strategy is validated.
Essential Components of Backtesting
To conduct effective backtesting, several key components are necessary:
- Quality Historical Data: The foundation of successful backtesting is reliable data. This includes:
- Price data: Open, high, low, close (OHLC) values.
- Corporate actions: Adjustments for stock splits and dividends.
- Market conditions: Information on market hours and holidays.
- Quantifiable Trading Rules: Your strategy must be translated into specific rules that can be programmed:
- Position Sizing: Determine how much capital to allocate per trade.
- Risk Management: Define stop-loss and take-profit parameters.
TradersPost connects seamlessly with platforms like TradingView, allowing you to automate these rules across multiple brokers such as Alpaca and Interactive Brokers.
Evaluating Risk Through Backtesting
One of the primary benefits of backtesting is uncovering potential risks before deploying real capital. By analyzing historical performance, traders can identify:
- Maximum Drawdown Periods: Understand the deepest declines in equity.
- Consecutive Losing Streaks: Prepare for psychological challenges.
- Volatility of Returns: Gauge the consistency of performance.
- Market Condition Dependencies: Recognize environments where strategies perform poorly.
Common Pitfalls in Backtesting
While backtesting is invaluable, several common mistakes can lead to misleading results:
- Survivorship Bias: Only testing securities that survived the testing period skews results. For instance, using only current S&P 500 constituents ignores delisted companies.
- Look-Ahead Bias: Using information not available at the time creates unrealistic scenarios. Avoid using future data or revised economic figures in historical simulations.
TradersPost executes the signals a strategy sends but does not run backtests, so avoiding these biases depends on how you build and test the strategy.
Measuring Strategy Performance
Backtesting provides quantitative measures to evaluate a strategy’s effectiveness:
- Total Return: Overall profit or loss percentage over time.
- Maximum Drawdown: Largest peak-to-trough decline experienced.
- Win Rate: Percentage of profitable trades executed.
- Profit Factor: Ratio of gross profits to gross losses.
Including transaction costs such as brokerage commissions and slippage in your analysis is critical. These factors can significantly impact performance outcomes over many trades.
Advanced Tools for Backtesting
Advanced platforms offer comprehensive features for thorough backtests:
- Platforms like QuantConnect provide cloud-based algorithmic trading solutions.
- TradingView includes a built-in Strategy Tester for testing trading ideas on historical data. Its free accounts can use backtesting features, although Bar Replay on free accounts is limited to daily, weekly, and monthly timeframes1.
For those who prefer coding their systems, TradersPost offers webhook integration to automate transitions from backtested strategies to live trading seamlessly across brokers like TradeStation and Tradier.
Implementing Best Practices
Following established best practices ensures reliable backtest results:
- Use point-in-time data that accurately reflects market conditions at each historical moment.
- Include relevant corporate actions such as dividends and stock splits in your simulations.
- Verify data accuracy against multiple sources to ensure reliability.
Incorporating transaction costs like bid-ask spreads and slippage effects ensures realistic profitability assessments. Proper position sizing relative to market liquidity minimizes adverse impacts on trade execution efficiency.
Conclusion
Backtesting is an indispensable tool for any trader seeking to validate their strategies without financial risk. By understanding its core components and avoiding common pitfalls, you can harness its full potential effectively. TradersPost acts as a vital bridge from theory to practice by enabling automated execution once a strategy has been rigorously tested. Whether you're transitioning from paper trading or diving into live markets with Alpaca or Interactive Brokers, TradersPost provides a streamlined workflow that bridges gaps between different platforms effortlessly. Start integrating smart automation into your trading today with TradersPost's powerful features at your disposal!