Types Of Slippage In Options Trading
Learn the types of slippage in options trading: negative, positive, and zero slippage, what causes each, and how order type and liquidity affect fills.
Marketing
The three main types of slippage in options are negative, positive, and zero slippage. Negative slippage produces a worse fill than expected, positive slippage produces a better fill, and zero slippage means the execution price matches the target price.
Options are especially exposed because spreads, liquidity, order book depth, volatility, and contract selection can change fill quality quickly. A strategy can identify the right direction and still underperform if execution costs consume its expected edge.
Understanding how slippage interacts with order type, moneyness, expiration, order size, and automated signal latency helps traders set realistic limits, improve fills, and test strategies under conditions that resemble live trading.
What Is Slippage In Options
Defining The Price Gap
Slippage is the difference between the price expected when an order is submitted and the price at which it is executed. It is not necessarily a broker error. It is a structural market cost created by changing quotes and competition for available liquidity.1
For example, if an option is quoted at a $1.00 bid and $1.20 ask, a trader might treat the $1.10 midpoint as the expected price. A market buy at $1.20 creates $0.10 of slippage relative to that expectation. The comparison price must therefore be recorded consistently, whether it is the midpoint, alert price, limit price, or current quote.
Why Options Are Especially Prone
Far out-of-the-money contracts and contracts approaching expiration often have fewer active participants, which can produce wider spreads. Stock options also tend to have wider spreads relative to price than liquid large-cap stocks. Published estimates place options market order slippage around 0.5-2% on tight spreads and 2-5% on wider spreads, compared with approximately 0.05-0.15% for large-cap stocks.2
These are reference ranges, not guarantees. A contract's current spread, displayed size, volume, and order book depth are more useful for evaluating a specific order.
Negative, Positive, And Zero Slippage
Negative Slippage Mechanics
Negative slippage occurs when a buy fills above the expected price or a sell fills below it. The result is a higher entry cost, lower exit proceeds, or a larger loss than planned. Retail traders encounter it most frequently with market orders, illiquid contracts, and sudden price movements.3
Positive Slippage And Price Improvement
Positive slippage is a fill better than the target price, also called price improvement. A buy might execute below the expected price, or a sell might execute above it. It can occur when liquidity improves between submission and execution.
Well-placed limit orders in active contracts can capture price improvement. A trader might submit a buy near the midpoint rather than crossing directly to the ask. A market maker may accept that price when the resulting exposure can be hedged efficiently.4
Zero Slippage And Price Gaps
Zero slippage means the actual fill exactly matches the expected price. It is possible, but traders should not make it the default assumption in testing.
Price gaps occur when the market skips a group of price levels, often after news or a market close. If the pre-gap price is no longer available, a market order cannot fill there and instead seeks the next available liquidity.5
What Causes Options Slippage
The Bid-Ask Spread Cost
The bid is the highest displayed price a buyer will pay, while the ask is the lowest displayed price a seller will accept. A market buy usually executes at the ask, and a market sell usually executes at the bid. This means immediate execution pays the spread.6
Measure the spread as a percentage of the option premium, not only in dollars. A $0.10 spread is 2% of a $5.00 option but 20% of a $0.50 option. The second contract requires a much larger move just to recover its execution cost.
Market Impact And Order Size
When an order exceeds the contracts available at the best quote, the remaining quantity fills at progressively worse levels. This is known as walking the book. The resulting average fill may be far from the quote visible when the order was submitted.7
Market impact becomes more important during illiquid hours, volatile conditions, and directional order imbalances. Order size is controllable, so traders can reduce impact by comparing intended quantity with displayed size and submitting smaller tranches when necessary.
Volatility, News, And Timing
Market makers may widen spreads around earnings, central bank decisions, and major economic releases to compensate for rapidly changing risk. The middle of the US session, approximately 10:30 AM through 3:00 PM Eastern, generally provides more stable options liquidity than the opening and closing periods.8
The first and last 30 minutes can produce wider spreads, while pre-market and after-hours conditions carry lower liquidity. A strategy should record time of day so its execution statistics reveal whether certain windows consistently produce poor fills.
Latency And Signal Delay
Timing slippage is the movement between signal generation and order execution. The latency factor is the physical time required for the signal to reach the exchange infrastructure. Processing, routing, and matching add to the total delay.9
A short delay may be insignificant in a stable contract but material during a fast move. Automated traders should retain the signal timestamp, alert price, order submission time, and actual fill to separate spread cost from latency-related movement.
Slippage Differences By Order Type
Market Orders And Guaranteed Fills
Market orders prioritize execution but provide no price protection. A market buy normally crosses to the ask, while a market sell crosses to the bid. If available size is insufficient, the order can continue through worse price levels.
This makes market orders the most slippage-prone order type, particularly in illiquid options. They may still be appropriate when an urgent risk reduction matters more than execution price.
Limit Orders And Price Control
A buy limit establishes the maximum acceptable price, while a sell limit establishes the minimum. This caps negative price deviation but creates non-fill risk. An order can remain open or miss the trade if the market never reaches its limit.10
For non-urgent entries, traders can begin near the midpoint and adjust toward the ask when buying or toward the bid when selling. This balances price improvement against fill probability.
Stop-Limit Orders For Protection
A stop-limit order combines a stop price that activates the order with a limit price that defines the worst acceptable fill. It can prevent a standard stop from becoming a market order and executing far beyond the intended level during a fast move.11
The trade-off is serious: if price moves through the limit without available liquidity, the position may remain open. Stop-limit orders control execution price, not exit certainty.
Slippage And Contract Liquidity
Moneyness And Spread Width
Near-the-money contracts usually attract more activity than far out-of-the-money contracts. Deep in-the-money and deep out-of-the-money options can have lower volume and limited order book depth, increasing the chance that a large market order fills far from the midpoint.12
Expiration Timing Effects
Near-term monthly contracts tend to be more liquid than longer-dated contracts, although liquidity varies by underlying and listed expiration. Contracts approaching expiration may also have fewer active participants. Options in their final day lose time value rapidly, adding price risk to the execution risk already created by the spread.13
Volume And Open Interest Checks
Check volume, open interest, spread width, and displayed size before entering. Daily volume in the hundreds of contracts or more and higher open interest can indicate stronger participation. A spread below approximately 5-10% of the option price is a practical sign of workable liquidity, although the complete order book still matters.14
- Compare the spread with the option premium.
- Confirm displayed size can absorb the intended order.
- Check both daily volume and open interest.
- Review liquidity at the planned exit time.
Slippage In Multi-Leg Strategies
How Slippage Compounds Across Legs
Every leg creates another opportunity to pay the spread. A four-leg iron condor with $0.05 of slippage per leg incurs $0.20 when opened and another $0.20 when closed, for $0.40 of round-trip slippage. If its theoretical maximum return is $0.50 per share, execution consumes most of the expected edge.15
Combination Orders Versus Separate Legs
A single combination order controls the net price and avoids exposure between fills, but the combined spread may be wide. Dividing an iron condor into a put spread and call spread, with each submitted near its midpoint, can improve overall execution.
The cost of splitting is temporary directional exposure if one spread fills before the other. Traders must decide whether potential price improvement justifies that risk.
Setting Net Price Targets
Set a maximum net debit or minimum net credit before submitting the order. Base the target on realistic midpoint execution rather than the theoretical best price shown by analysis software. If the spread is too wide to support the strategy after costs, passing on the trade is an execution decision, not a missed opportunity.
Reducing Options Slippage
Trading Liquid, Near-Money Contracts
Options on widely traded stocks, index products, and large exchange-traded funds generally offer tighter spreads than contracts on thinly followed names. Near-the-money strikes often provide more participation and cleaner exits than distant strikes.
Placing Limits Near The Midpoint
Start a limit order at or near the mark price. If it does not fill, adjust in deliberate increments toward the ask when buying or toward the bid when selling. Establish the worst acceptable price before beginning so repeated adjustments do not turn the order into an uncontrolled marketable limit.
Splitting And Timing Large Orders
Break an order into smaller tranches when its quantity is large relative to displayed size. Avoid the minutes surrounding scheduled announcements, and consider waiting five to ten minutes for spreads to normalize. The first and last 30 minutes of the session also deserve additional scrutiny.
Using Slippage Tolerance Settings
A maximum price deviation or spread tolerance can reject an order instead of allowing an unexpectedly poor fill. Tight thresholds improve price control but increase non-fill risk, so the setting should reflect whether the strategy prioritizes fill quality or execution certainty.
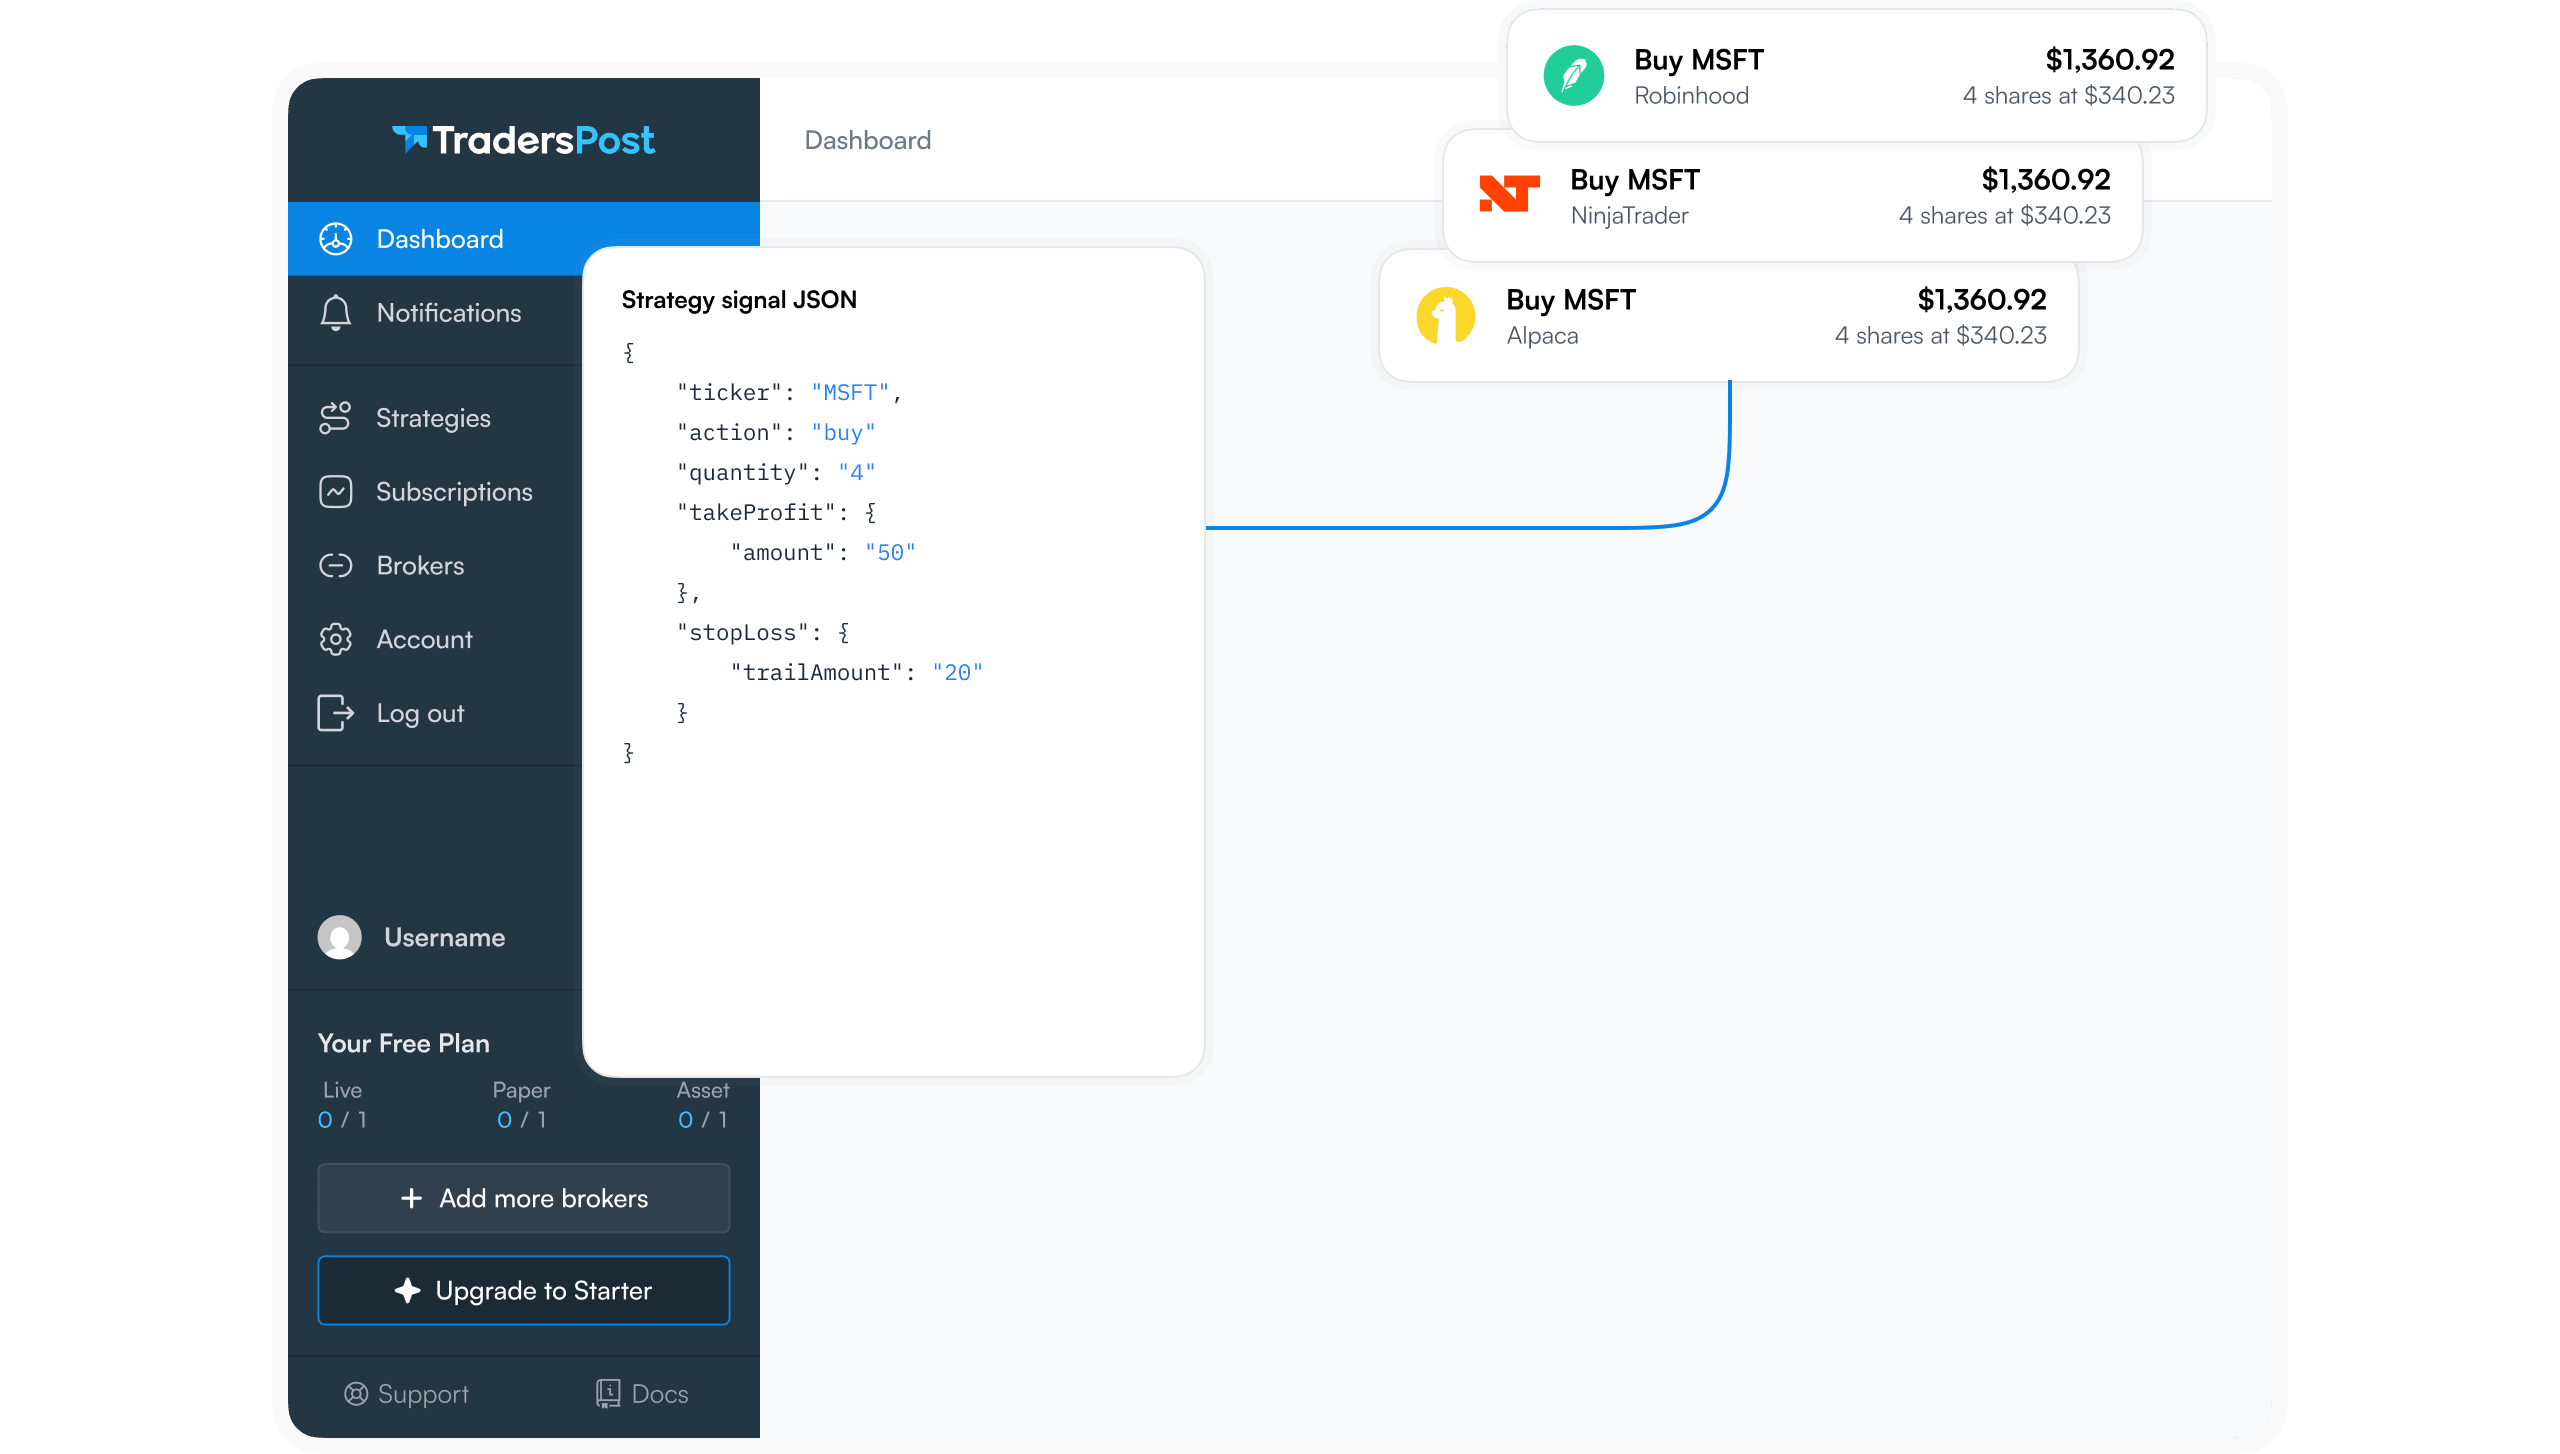
For automated directional options workflows, TradersPost webhook payloads can include either bidAskSpreadFilter for a dollar threshold or bidAskSpreadFilterPercent for a percentage threshold. An entry or exit is rejected when the applicable spread exceeds the value sent, and the two fields cannot be included together.
Apply Controls To Automation
See how TradersPost spread filters and signal price fields can fit into an automated options workflow, then test the thresholds with paper execution before applying them to live orders.
Tracking And Testing Slippage
Logging Expected And Actual Fills
Maintain a log containing the alert price, target price, bid, ask, order type, quantity, submission time, and actual fill. Calculate slippage separately for buys and sells so the sign is interpreted correctly.
Segment the results by contract moneyness, expiration, time of day, and order type. This reveals whether poor fills are isolated events or a repeated weakness in the strategy's execution process.
Backtests That Ignore Slippage Mislead
Backtests that use midpoint prices can materially overstate real-world performance. One published illustration shows how a strategy returning 12% annually with an assumed 0.5% slippage could produce only 3-4% live if actual slippage reaches 1.5%.16
Paper platforms may also fill orders instantly at requested prices while ignoring market depth, latency, and liquidity gaps. That creates an idealized result rather than a realistic execution test.17
Configuring Realistic Paper Trading
Match paper slippage assumptions to published broker execution statistics where possible. Use a higher estimate for market orders and a lower estimate for limit orders, while modeling the possibility that a limit order never fills.18
When a TradersPost webhook includes price or signalPrice, the value records the market price at signal time and can be used to calculate slippage against the actual fill. Including the time field also supports latency tracking in signal logs.
Bottom Line
- Negative, positive, and zero slippage describe fills worse than, better than, or equal to the expected price.
- The bid-ask spread is usually the largest options execution cost.
- Limit orders control price but can remain unfilled.
- Liquidity, order size, timing, and latency should be tested together.
- Automated strategies need spread filters and recorded signal prices, not optimistic midpoint assumptions.
Conclusion
Options slippage cannot be eliminated, but it can be measured and controlled. Favor liquid contracts, compare spreads as a percentage of premium, use limits when price matters, divide oversized orders, and avoid unstable liquidity windows.
The next step is to review a sample of recent fills and calculate the difference between each signal price and execution price. Use that evidence to set contract filters, order rules, and realistic testing assumptions before increasing size or automating live execution.
Frequently Asked Questions
Why Is Options Slippage Worse?
Options spreads are often wider relative to price, particularly for far out-of-the-money or near-expiration contracts. Market order slippage estimates are approximately 0.5-2% on tight options spreads and 2-5% on wider spreads, compared with 0.05-0.15% for liquid large-cap stocks.
Can Slippage Be Completely Avoided?
No. Slippage is a structural trading cost. Traders can reduce its impact by selecting liquid contracts, controlling order size, using appropriate limit prices, and avoiding volatile periods.
Are Limit Orders Always Better?
No. Limit orders control execution price but may not fill. Market orders prioritize execution but offer no price protection, which can make them appropriate for urgent exits or highly liquid contracts.
How Much Slippage Is Typical?
Published estimates place options market order slippage around 0.5-2% for tight spreads and 2-5% for wider spreads. Actual results depend on the contract, spread, size, volatility, timing, and order type.
How Do I Check Liquidity?
Review daily volume, open interest, displayed size, and the spread as a percentage of the premium. Hundreds of contracts in daily volume, stronger open interest, and a spread below roughly 5-10% of the option price are practical signs of workable liquidity.
References
- 1 Fill Quality & Slippage Tactics for Better Options Fills
- 2 Paper Trading: Realistic Slippage and Execution Costs
- 3 Minimize Slippage: Control Execution Risk
- 4 Fill Quality & Slippage Tactics for Better Options Fills
- 5 Minimize Slippage: Control Execution Risk
- 6 Understanding the Bid and Ask Prices for Options
- 7 Fill Quality & Slippage Tactics for Better Options Fills
- 8 Fill Quality & Slippage Tactics for Better Options Fills
- 9 Minimize Slippage: Control Execution Risk
- 10 Understanding the Bid and Ask Prices for Options
- 11 Minimize Slippage: Control Execution Risk
- 12 Bid-Ask Spreads and Slippage in U.S. Equity Options
- 13 Bid-Ask Spreads and Slippage in U.S. Equity Options
- 14 Bid-Ask Spreads and Slippage in U.S. Equity Options
- 15 Fill Quality & Slippage Tactics for Better Options Fills
- 16 Paper Trading: Realistic Slippage and Execution Costs
- 17 Minimize Slippage: Control Execution Risk
- 18 Paper Trading: Realistic Slippage and Execution Costs